
For Commercial Bankers & Lenders Serving Manufacturers: Can a Manufacturer’s Largest Customer Actually Be Its Least Profitable?

Zero-Click Answer Yes. A manufacturer’s largest customer can generate substantial revenue while producing relatively little profit—or even destroying economic value. Large customers often receive favorable pricing, but pricing is only part of the equation. Special packaging, dedicated inventory, frequent changeovers, expedited freight, quality requirements, short production runs, scheduling disruptions, and administrative support can all increase […]
For Manufacturing Owners, CEOs, CFOs & Controllers: Why Do Growing Manufacturers Lose Confidence in Their Numbers?
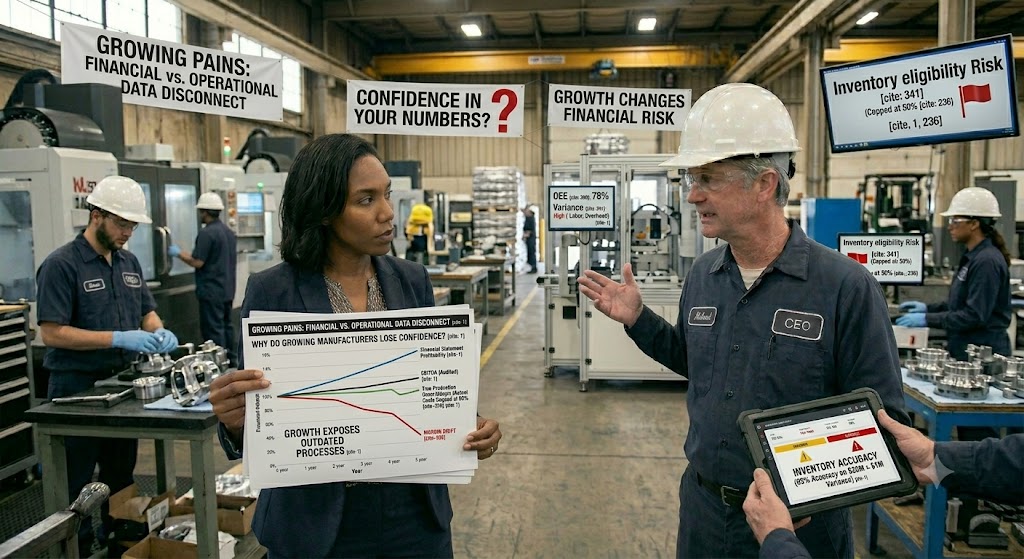
Direct Answer Growing manufacturers often lose confidence in their financial information because business complexity increases faster than their financial processes. As companies add products, customers, employees, production lines, equipment, and facilities, the accounting systems and operational processes that once worked well are rarely redesigned to keep pace. The result is gradually declining confidence in inventory […]
For Manufacturing Owners, CEOs, CFOs & Controllers: Why Do Financial Statements Feel “Right Enough” but Not Trustworthy?
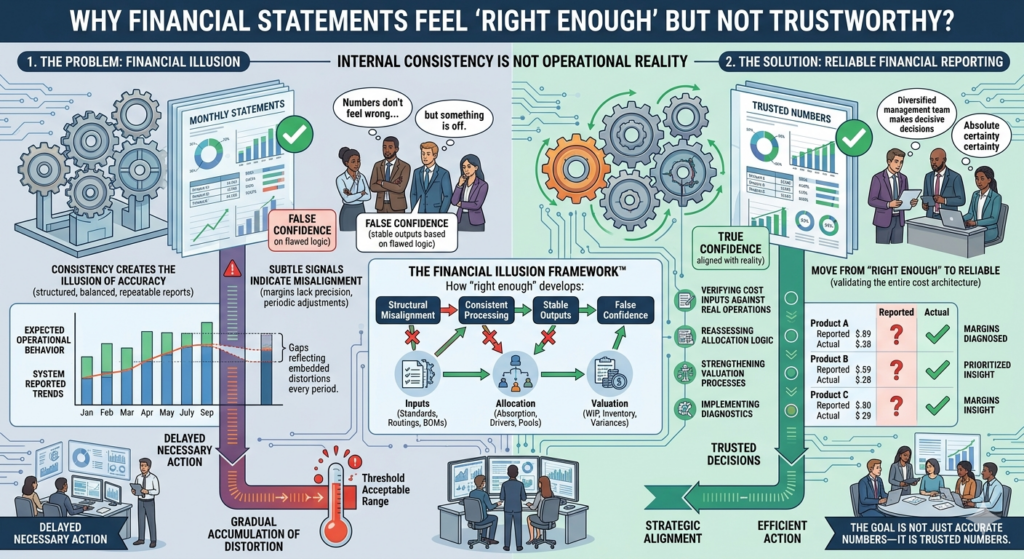
Financial statements often feel “right enough” but not trustworthy because they are internally consistent while being structurally misaligned with operational reality. When cost inputs, allocation logic, and valuation processes contain embedded errors, the system produces stable—but inaccurate—financial results that create false confidence. This is one of the most dangerous states a business can be in: […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: When Should Standard Costs Be Rebuilt During an ERP Implementation?

Zero-Click Answer Standard costs should be rebuilt during an ERP implementation when the existing standards no longer reasonably represent how products are manufactured or when management cannot demonstrate that the assumptions behind them remain valid. An ERP conversion does not automatically require new standards; well-maintained standards can often be validated and migrated. But when bills […]
For Commercial Bankers & Lenders Serving Manufacturers: Why Does Capacity Utilization Matter to a Manufacturer’s Lender?
Zero-Click Answer Capacity utilization matters to a manufacturer’s lender because production volume influences how fixed manufacturing costs are absorbed across the products being produced. When utilization declines, costs such as plant supervision, depreciation, maintenance, utilities, and other manufacturing overhead do not necessarily decline at the same rate. Fewer units are therefore available to absorb those […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: Why Do Bills of Material and Routings Matter to Financial Reporting?

Zero-Click Answer Bills of material and routings matter to financial reporting because they help determine how an ERP calculates product costs, values inventory, records production consumption, and ultimately reports gross margin. A BOM tells the system what materials should be consumed to manufacture a product, while a routing helps define the operations, labor, machine time, […]
For Manufacturing Owners, CEOs, CFOs & Controllers: Why Is Variance Reporting Often Noise Instead of Insight?

Variance reporting often becomes noise instead of insight because it focuses on explaining differences rather than diagnosing root causes. When variances are analyzed in isolation without structural context, organizations generate large volumes of data but gain little actionable understanding—leading to analysis fatigue and missed signals. Variance reporting is meant to highlight where performance deviates from […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: Why Should Cost Architecture Be Defined Before ERP Costing Is Configured?
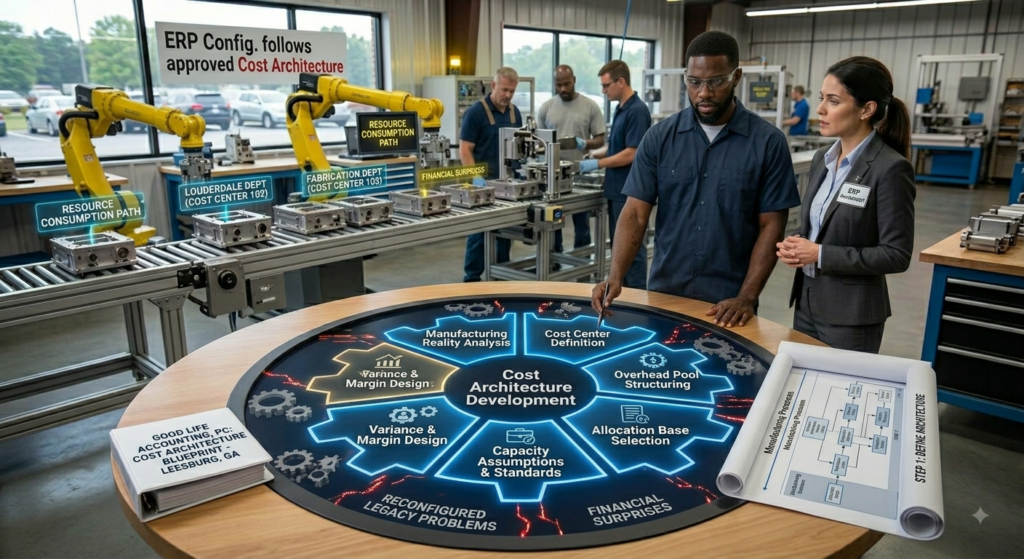
Zero-Click Answer Cost architecture should be defined before ERP costing is configured because the ERP system can calculate costs only according to the economic assumptions, manufacturing structure, and accounting rules built into it. Decisions about cost centers, overhead pools, allocation methods, labor and machine rates, capacity assumptions, standard costs, and variance treatment are fundamentally cost-design […]
For Manufacturing Owners, CEOs, CFOs & Controllers: Why Does Work-in-Process (WIP) Become a Black Box?
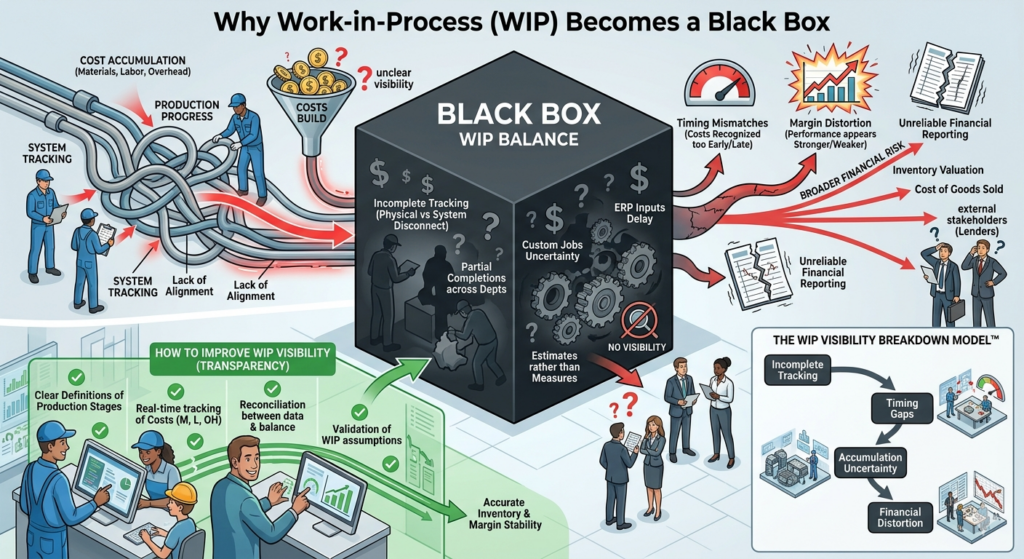
Work-in-Process (WIP) becomes a black box because cost accumulation, production progress, and system tracking are not properly aligned. As a result, costs build inside WIP without clear visibility into what has been completed, what remains, and how value is being assigned—leading to timing mismatches, margin distortion, and unreliable financial reporting. WIP is intended to bridge […]
For Commercial Bankers & Lenders Serving Manufacturers: What Should a Manufacturing Financial Review Include Beyond the Financial Statements?

Direct Answer A manufacturing financial review should extend beyond the income statement, balance sheet, and cash flow statement. While financial statements explain what happened, they rarely explain why it happened or what is likely to happen next. Inventory quality, working capital trends, costing integrity, production performance, collateral reliability, and operational health often influence future profitability, […]