
Why Are Inventory Adjustments a Cost System Red Flag (Not Just a Cleanup Issue?)
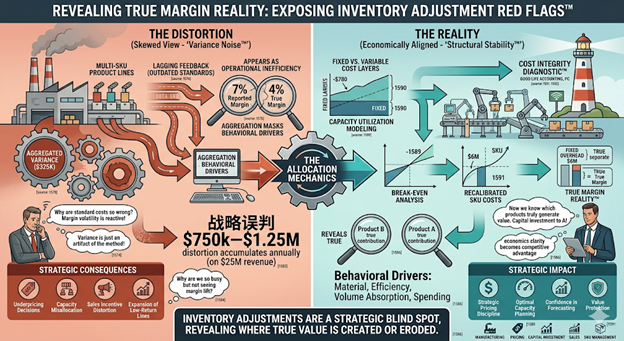
Inventory adjustments are often treated as routine accounting entries—something to fix discrepancies and move on. But that perspective misses the real issue. Inventory adjustments are not just corrections—they are signals. Frequent or unexplained adjustments indicate breakdowns in cost flow, transaction discipline, or system alignment, making them one of the clearest indicators that a costing system […]
Why Do Variances Stop Being Useful (and What Does That Signal About Your Cost System?)
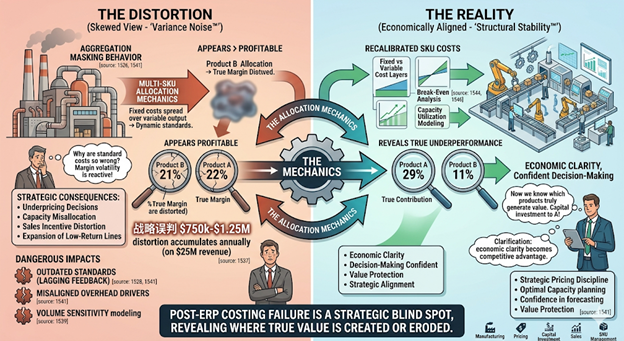
Variance analysis is supposed to be one of the most powerful tools in a manufacturing business. It highlights changes, surfaces issues, and drives corrective action. But in many companies, variances are still reported—yet no longer useful. Variances stop being useful when the underlying standards are no longer aligned with operational reality. When that happens, variances […]
Why Do Manufacturing ERP Implementations Fail Even When the Software Works?
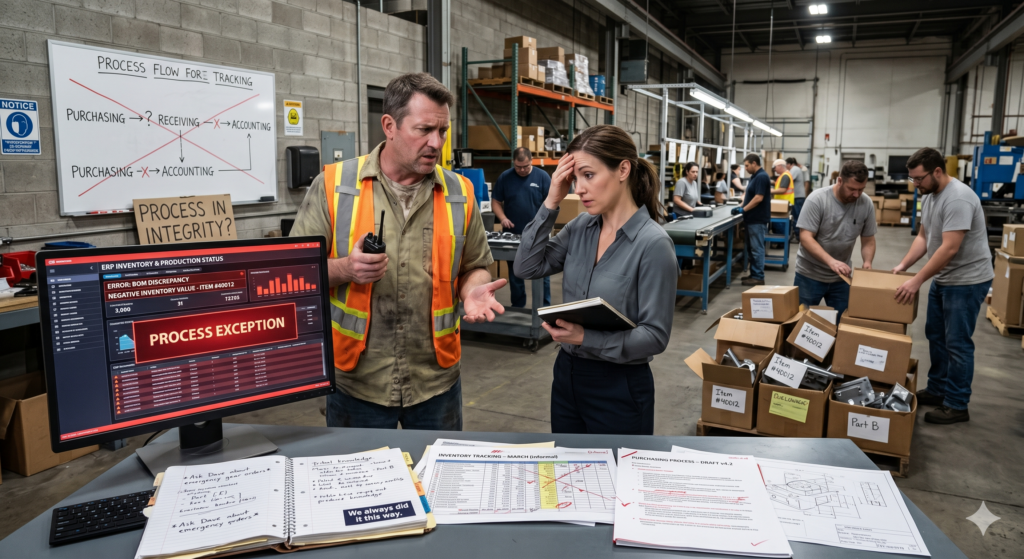
Direct Answer Most manufacturing ERP implementations fail because of process, data, inventory, and costing problems—not because of software problems. In most cases, the ERP system performs exactly as designed, but the organization lacks documented workflows, reliable master data, accurate inventory records, clear ownership, or current costing structures. When an ERP system automates poorly understood processes, […]
Why Do Inventory Shrink Losses Surprise Manufacturing Companies?
Manufacturing inventory is expected to experience some level of loss over time. Material scrap, handling damage, yield loss, and occasional obsolescence are normal economic realities of production environments. However, many costing systems treat these losses as unexpected events rather than predictable cost behavior. Shrink blind spots occur when expected inventory loss is not structurally modeled […]
How Does WIP Compression Risk Distort Manufacturing Margins?
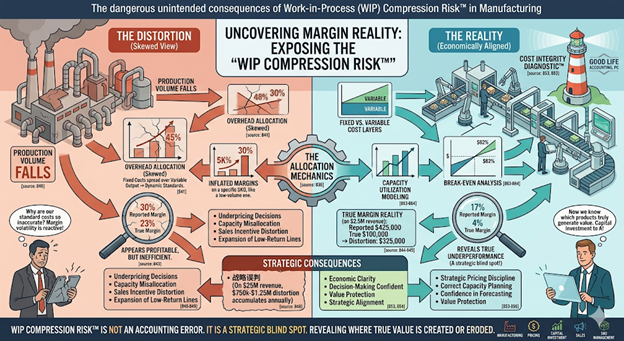
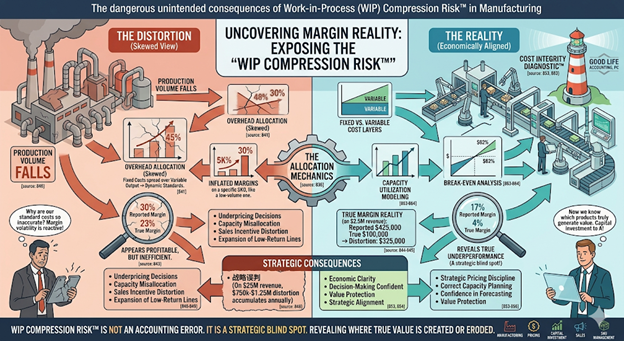
Work-in-process (WIP) inventory sits at the center of manufacturing financial reporting. It represents partially completed production that contains materials issued, labor applied, and overhead absorbed before the final product is finished. Because WIP sits between cost recognition and revenue recognition, even small valuation misalignments can affect reported margins. WIP Compression Risk occurs when work-in-process inventory […]
Why Do Manufacturing Inventory Balances Become Unstable?

Inventory is more than a balance sheet asset in manufacturing. It is a layered economic model that carries raw materials, absorbed labor, overhead allocation, and standard cost assumptions through the production system. When those underlying assumptions drift away from operational reality, inventory behavior becomes unstable. Inventory instability occurs when inventory valuation no longer moves predictably […]
The True Cost of “Close Enough” Inventory Counts

When inventory accuracy is optional, the damage shows up everywhere — margins, borrowing base, year-end surprises.