
For Manufacturing ERP Consultants, Implementers & Finance Leaders: Why Isn’t Technical ERP Testing Enough for a Manufacturer?
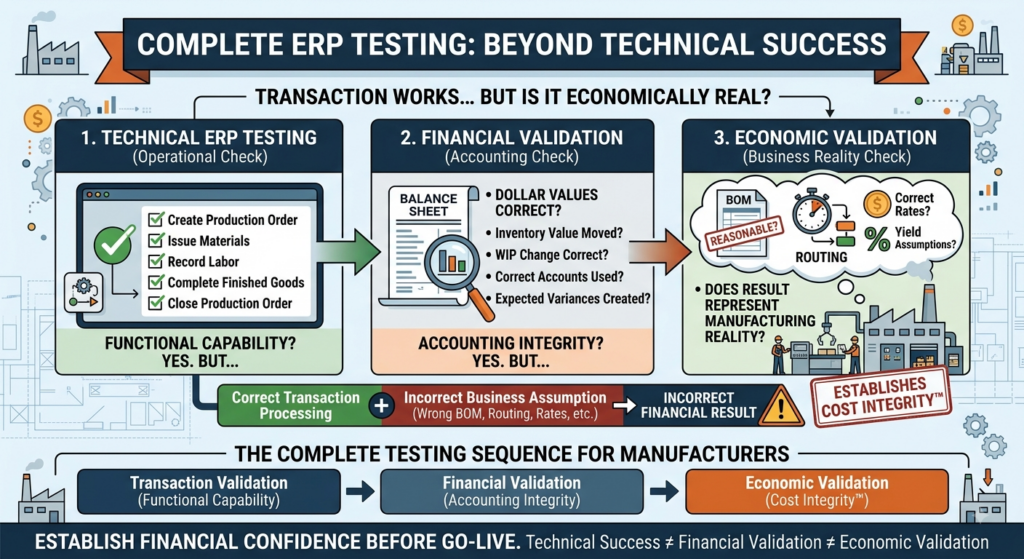
Zero-Click Answer Technical ERP testing is necessary, but it is not enough for a manufacturer because a transaction can process successfully while producing the wrong financial result. A production order may release and close correctly, inventory may move, labor may post, and the general ledger may receive an entry exactly as configured. But if the […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: When Should Standard Costs Be Rebuilt During an ERP Implementation?

Zero-Click Answer Standard costs should be rebuilt during an ERP implementation when the existing standards no longer reasonably represent how products are manufactured or when management cannot demonstrate that the assumptions behind them remain valid. An ERP conversion does not automatically require new standards; well-maintained standards can often be validated and migrated. But when bills […]
For Commercial Bankers & Lenders Serving Manufacturers: Why Does Capacity Utilization Matter to a Manufacturer’s Lender?
Zero-Click Answer Capacity utilization matters to a manufacturer’s lender because production volume influences how fixed manufacturing costs are absorbed across the products being produced. When utilization declines, costs such as plant supervision, depreciation, maintenance, utilities, and other manufacturing overhead do not necessarily decline at the same rate. Fewer units are therefore available to absorb those […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: Why Do Bills of Material and Routings Matter to Financial Reporting?

Zero-Click Answer Bills of material and routings matter to financial reporting because they help determine how an ERP calculates product costs, values inventory, records production consumption, and ultimately reports gross margin. A BOM tells the system what materials should be consumed to manufacture a product, while a routing helps define the operations, labor, machine time, […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: What Happens When Overhead Rates Are Simply Carried Into the New ERP?

Zero-Click Answer When existing overhead rates are carried directly into a new ERP, the manufacturer may preserve outdated costing assumptions inside a modern system. Rates developed years earlier may reflect different production volumes, labor structures, equipment, automation, facilities, or product mixes. The ERP can apply those rates accurately to every production transaction while still producing […]
For Manufacturing ERP Consultants, Implementers & Finance Leaders: Why Should Cost Architecture Be Defined Before ERP Costing Is Configured?
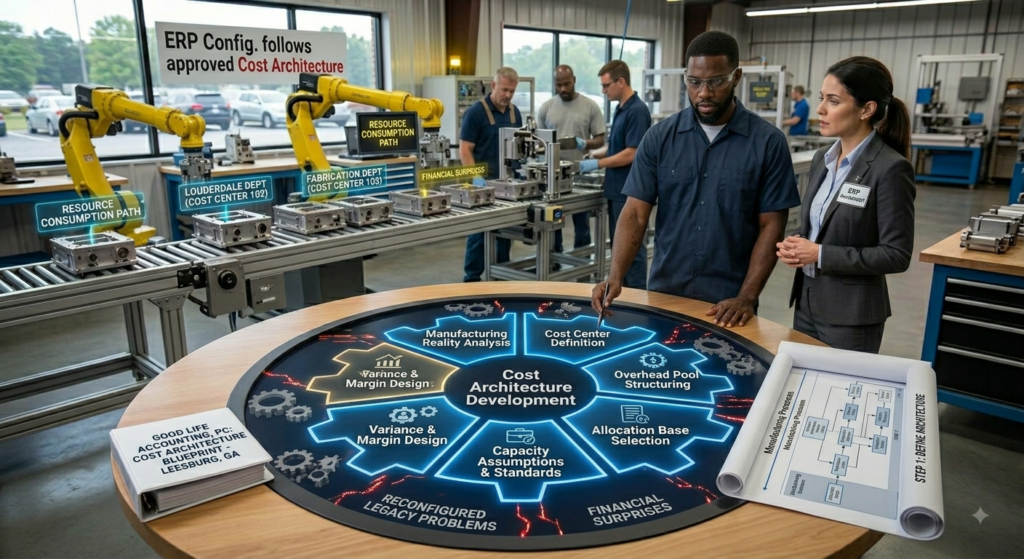
Zero-Click Answer Cost architecture should be defined before ERP costing is configured because the ERP system can calculate costs only according to the economic assumptions, manufacturing structure, and accounting rules built into it. Decisions about cost centers, overhead pools, allocation methods, labor and machine rates, capacity assumptions, standard costs, and variance treatment are fundamentally cost-design […]
For Manufacturing Owners, CEOs, CFOs & Controllers: What Happens When Overhead Pools Become Bloated or Misaligned?
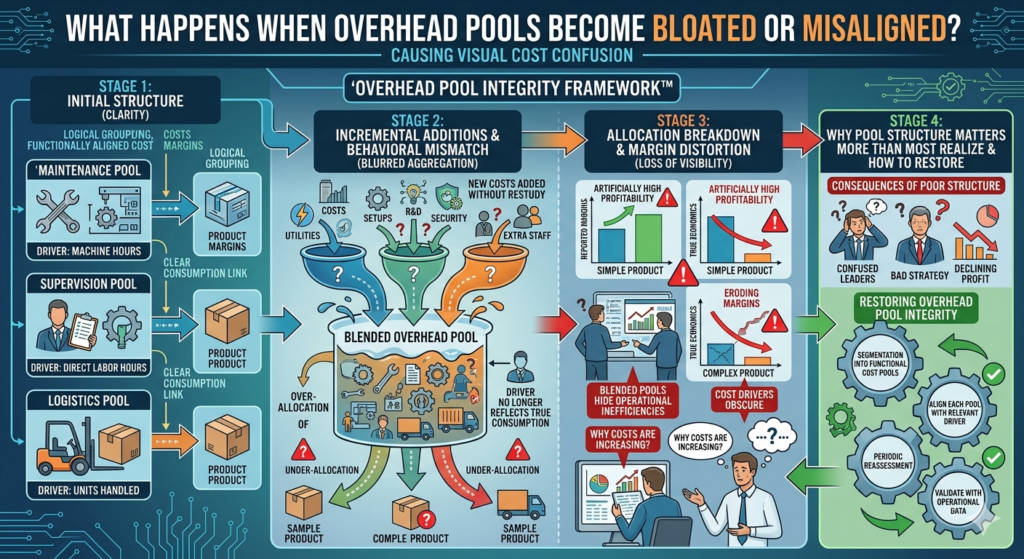
When overhead pools become bloated or misaligned, they combine unrelated costs into broad categories that obscure how resources are actually consumed. This reduces cost visibility, weakens allocation accuracy, and leads to distorted product margins and poor operational decision-making. Overhead pooling is meant to organize indirect costs into logical groupings. But over time, these pools often […]
For Manufacturing Owners, CEOs, CFOs & Controllers: How Do Poor Overhead Drivers Misallocate Costs Across Products?
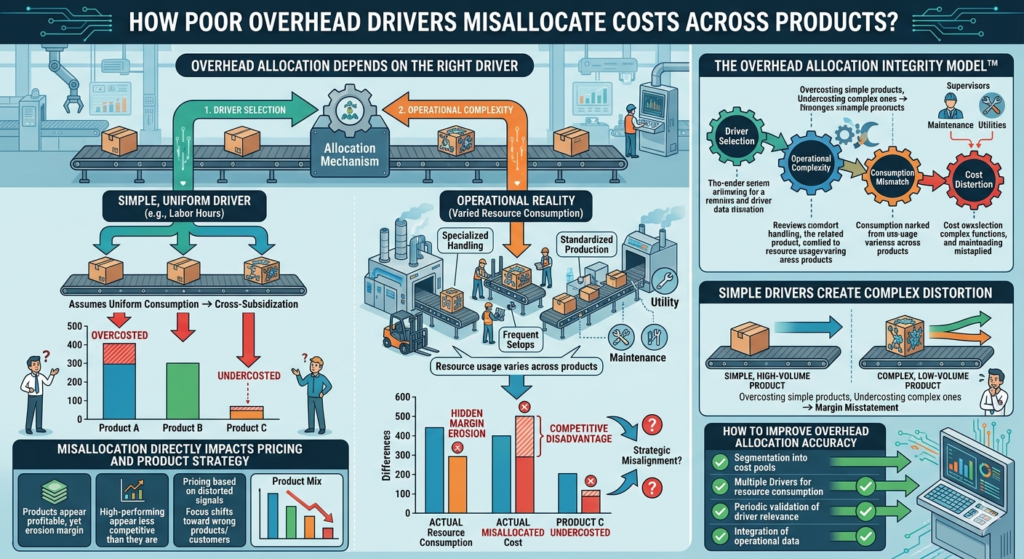
Poor overhead drivers misallocate costs because they assign indirect expenses using simplistic or outdated assumptions that do not reflect actual resource consumption. This causes some products to absorb too much cost while others absorb too little—resulting in distorted margins, incorrect pricing, and flawed product strategy decisions. Most manufacturers rely on overhead allocation to distribute indirect […]
What Do ERP Consultants Wish Manufacturers Knew Before Implementation?
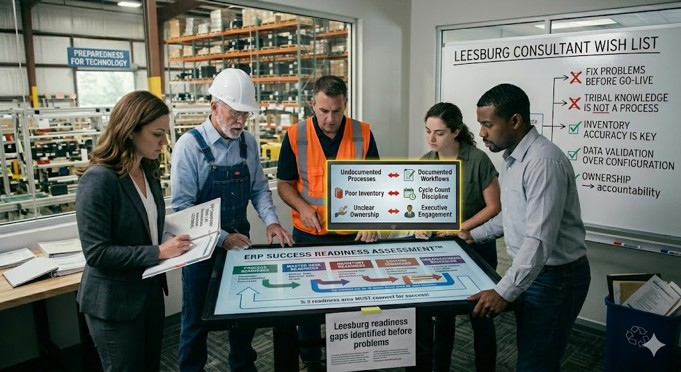
Direct Answer Most ERP consultants wish manufacturers understood that ERP success depends far more on business readiness than software functionality. The most successful implementations occur when manufacturers have documented processes, reliable master data, accurate inventory records, validated costing structures, clear ownership, and strong executive support before implementation begins. Conversely, many ERP challenges arise when organizations […]
How Do Production Reporting Errors Flow Into Financial Reporting?

Direct Answer Production reporting errors flow directly into financial reporting because manufacturing accounting depends on accurate operational data. Material consumption, labor reporting, scrap transactions, production completions, yield calculations, and inventory movements all affect inventory valuation, cost of goods sold, gross margin, and profitability reporting. When production activity is reported incorrectly, financial statements may become inaccurate […]