
If a Manufacturing Company Passed Its Audit, Can the Operational Data Still Be Wrong?
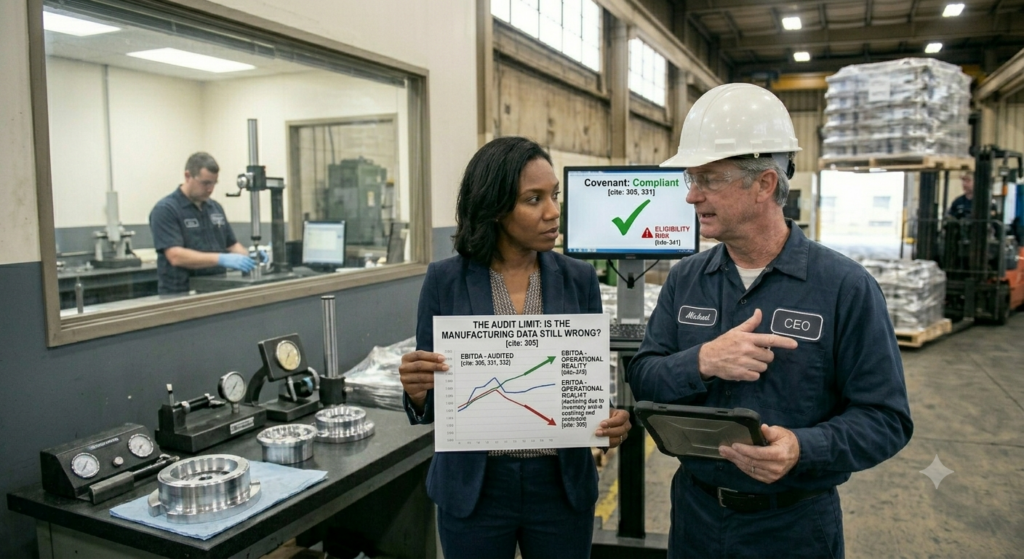
Direct Answer Yes. A manufacturing company can receive a clean audit opinion while still operating with inaccurate inventory records, outdated standard costs, declining production yields, inaccurate routings, or unreliable operational reporting. An audit provides assurance that financial statements are fairly presented in accordance with accounting standards. It does not necessarily validate every operational assumption used […]
How Do Manufacturing Costing Problems Become Covenant Problems?
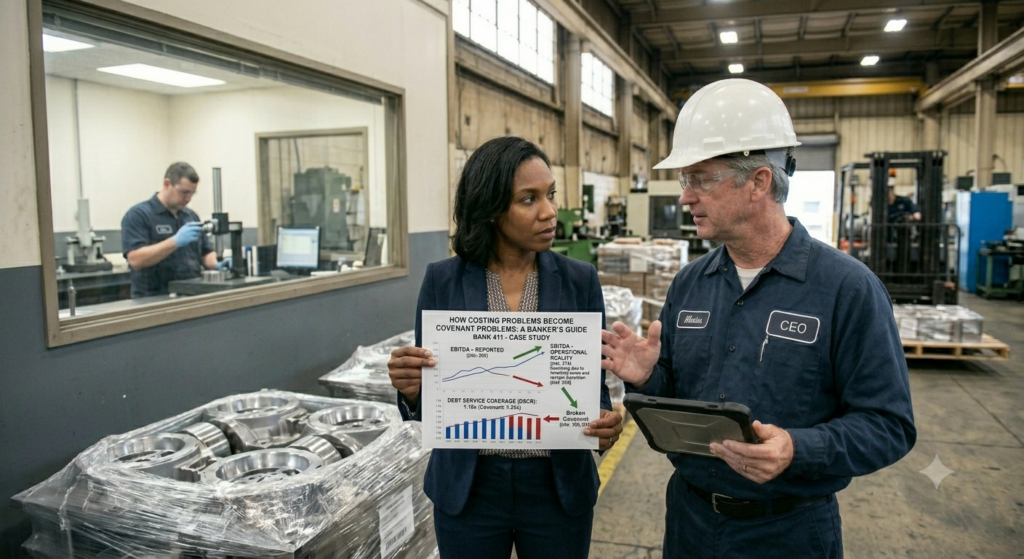
Direct Answer Manufacturing costing problems become covenant problems when inaccurate cost information flows through inventory valuation, gross margin, EBITDA, borrowing base calculations, and financial ratios. What begins as a small operational issue—such as outdated standard costs, inventory inaccuracies, declining yields, or improper overhead allocations—can gradually distort financial reporting. By the time a covenant violation occurs, […]
Why Do Manufacturing Cost Systems Drift Without Executive Cost Governance?
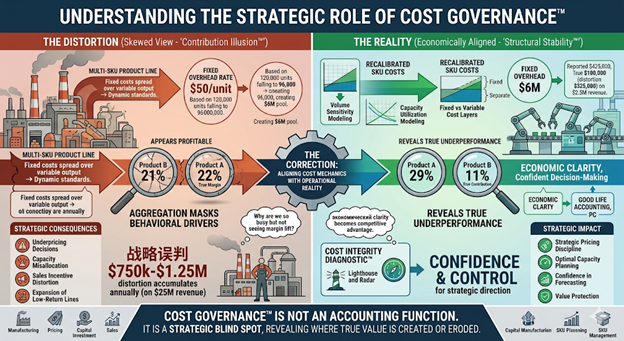
Manufacturing companies invest heavily in ERP systems, costing models, and financial reporting frameworks. These systems are designed to track materials, labor, overhead, and product margins with precision. However, as production environments evolve, the cost architecture that supports those reports often remains unchanged. Cost governance is the executive discipline of actively overseeing and periodically validating whether […]
Why Do Inventory Valuation Errors Create Lending Risk for Manufacturers?
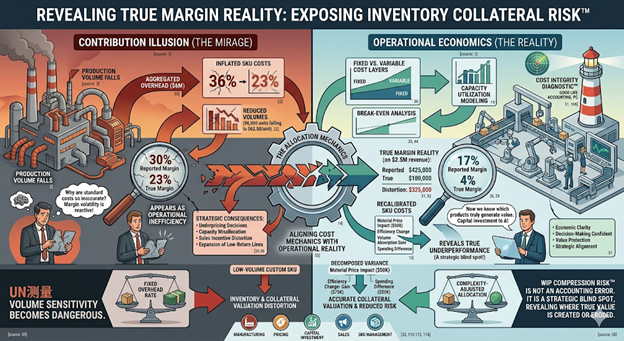
For many manufacturing companies, inventory serves two roles at the same time. It is both an operational asset supporting production and a financial asset supporting working capital financing. Banks often lend against inventory balances through borrowing base structures that assume the reported values are reliable and economically aligned with production activity. Inventory collateral risk occurs […]