
Why Do Variances Stop Being Useful (and What Does That Signal About Your Cost System?)
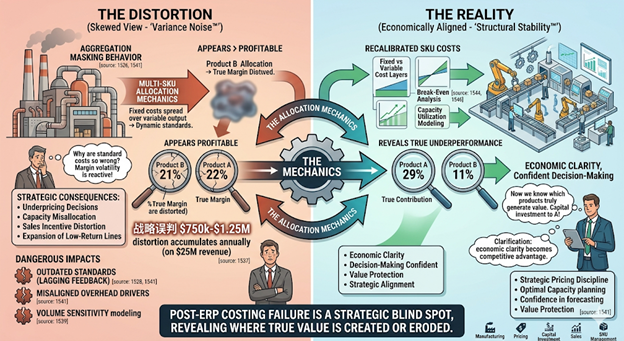
Variance analysis is supposed to be one of the most powerful tools in a manufacturing business. It highlights changes, surfaces issues, and drives corrective action. But in many companies, variances are still reported—yet no longer useful. Variances stop being useful when the underlying standards are no longer aligned with operational reality. When that happens, variances […]
What Are the Early Warning Signs Your Costing System Is Failing?
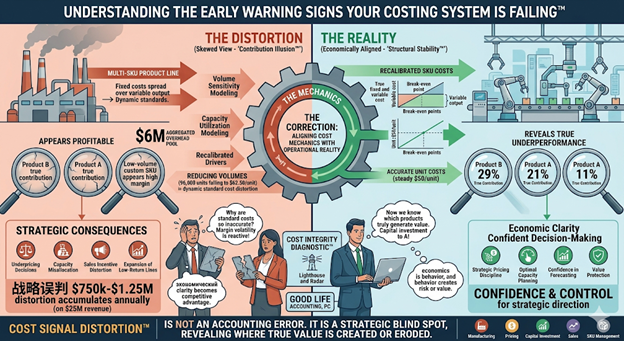
Most costing systems don’t fail all at once—they drift. The challenge is that by the time the problem is obvious, the financial impact is already embedded in your margins, inventory, and pricing decisions. The early warning signs of a failing costing system include stable but misleading margins, recurring unexplained variances, frequent inventory adjustments, and growing […]
Why Do Manufacturing Cost Systems Drift Without Executive Cost Governance?
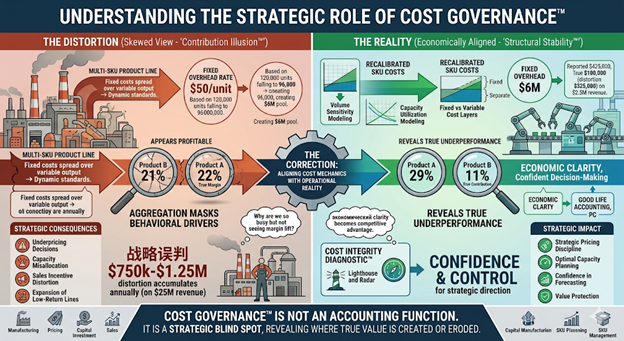
Manufacturing companies invest heavily in ERP systems, costing models, and financial reporting frameworks. These systems are designed to track materials, labor, overhead, and product margins with precision. However, as production environments evolve, the cost architecture that supports those reports often remains unchanged. Cost governance is the executive discipline of actively overseeing and periodically validating whether […]
Why Do Inventory Valuation Errors Create Lending Risk for Manufacturers?
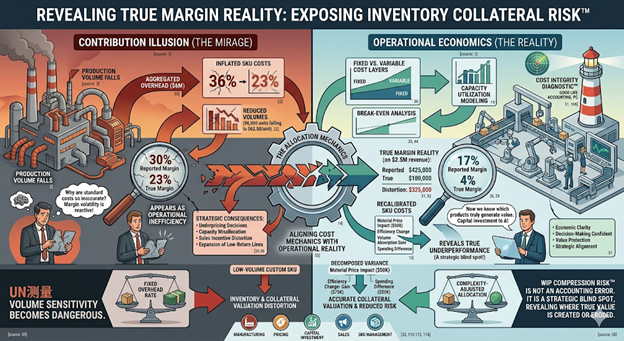
For many manufacturing companies, inventory serves two roles at the same time. It is both an operational asset supporting production and a financial asset supporting working capital financing. Banks often lend against inventory balances through borrowing base structures that assume the reported values are reliable and economically aligned with production activity. Inventory collateral risk occurs […]
Why Do Manufacturing Cost Reports Sometimes Send the Wrong Signals?
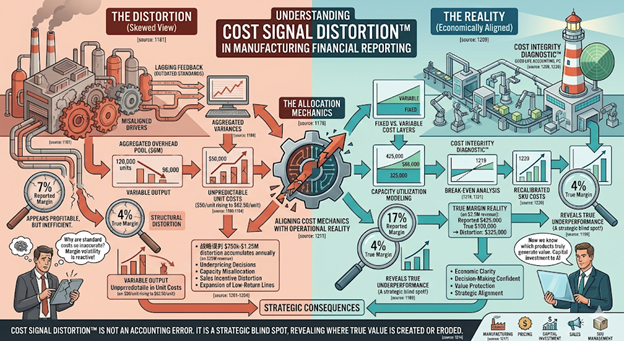
Manufacturing leaders rely on financial reports to guide pricing decisions, production planning, capital investment, and product strategy. Margin analysis, SKU contribution reports, and variance reports are designed to translate operational activity into clear economic insight. Cost signal distortion occurs when internal financial reports appear precise but communicate misleading economic signals due to structural misalignment in […]
Why Do Manufacturing Variance Reports Stop Providing Useful Insight?
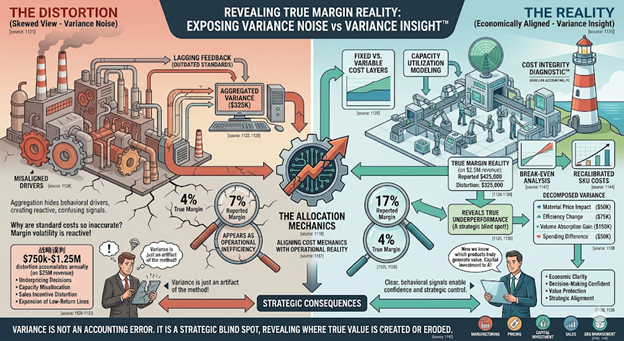
Manufacturing financial systems generate large volumes of variance data every month. Reports often include material price variance, labor efficiency variance, overhead spending variance, and production volume variance. In theory, these reports help management understand operational performance. Variance noise occurs when variance reports generate activity but not economic understanding. Instead of revealing meaningful changes in production […]
Why Do Inventory Shrink Losses Surprise Manufacturing Companies?
Manufacturing inventory is expected to experience some level of loss over time. Material scrap, handling damage, yield loss, and occasional obsolescence are normal economic realities of production environments. However, many costing systems treat these losses as unexpected events rather than predictable cost behavior. Shrink blind spots occur when expected inventory loss is not structurally modeled […]
How Does WIP Compression Risk Distort Manufacturing Margins?
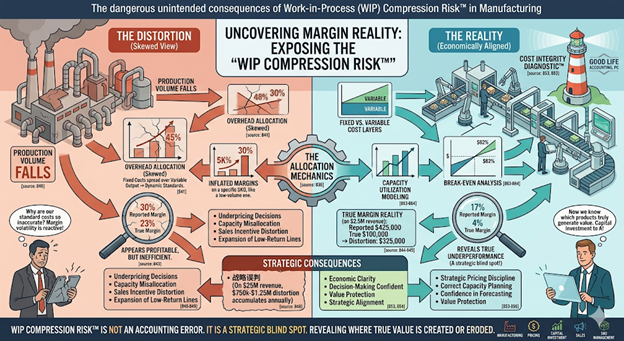
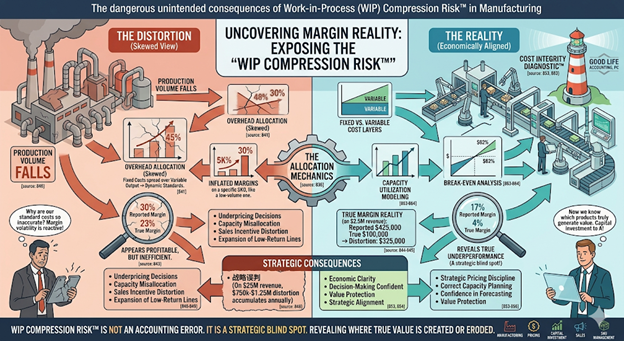
Work-in-process (WIP) inventory sits at the center of manufacturing financial reporting. It represents partially completed production that contains materials issued, labor applied, and overhead absorbed before the final product is finished. Because WIP sits between cost recognition and revenue recognition, even small valuation misalignments can affect reported margins. WIP Compression Risk occurs when work-in-process inventory […]
Why Do Manufacturing Inventory Balances Become Unstable?

Inventory is more than a balance sheet asset in manufacturing. It is a layered economic model that carries raw materials, absorbed labor, overhead allocation, and standard cost assumptions through the production system. When those underlying assumptions drift away from operational reality, inventory behavior becomes unstable. Inventory instability occurs when inventory valuation no longer moves predictably […]
What Is Structural Instability in Manufacturing Cost Systems?
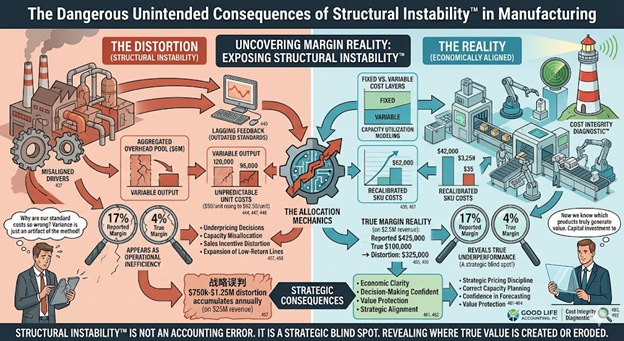
Every manufacturing company operates on an underlying cost structure that connects materials, labor, overhead, production flow, and volume behavior. This structure forms the foundation for pricing, margin analysis, and operational decision-making. Over time, however, businesses evolve while their cost systems often remain anchored to older assumptions. Structural instability occurs when a manufacturing cost system no […]